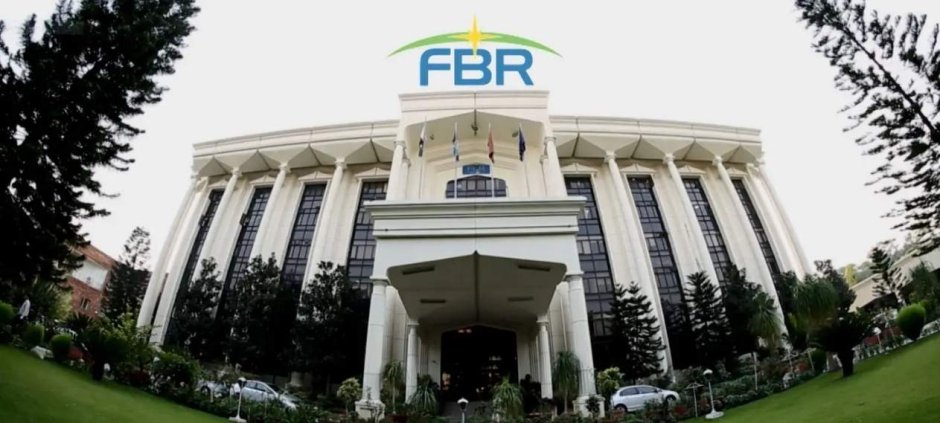
The Federal Board of Revenue (FBR) has clarified that a pending tax case does not prevent authorities from pursuing a separate money-laundering investigation.
According to a statement issued by the tax authority on Sunday, the Lahore High Court (LHC) has ruled that investigators do not have to wait for a tax case to reach its conclusion before proceeding with a money-laundering investigation.
The court’s decision establishes that tax proceedings and money-laundering investigations can continue independently when the relevant legal requirements are met.
LHC clarifies separate legal proceedings
The FBR said the LHC treated money laundering as a separate offence from the underlying tax matter.
This means that the existence of a pending tax dispute does not automatically prevent investigators from examining whether funds were obtained, transferred or handled through activities that may fall under money-laundering laws.
The ruling also allows proceedings relating to taxation and alleged money laundering to move forward simultaneously rather than requiring one process to be completed before the other begins.
The distinction is significant because tax cases generally concern the assessment, collection or recovery of taxes, while money-laundering investigations focus on the source and movement of potentially illicit funds.
FBR investigation powers
According to the FBR statement, its Intelligence and Investigation wing has the authority to register money-laundering cases and conduct investigations in accordance with the law.
The tax authority said that investigators are not required to obtain a prior conviction for the underlying offence before initiating or pursuing a money-laundering case.
The position means that an investigation into suspected financial activity can proceed even while the related tax proceedings remain unresolved.
However, the continuation of an investigation does not itself establish that an individual or entity is guilty. The determination of liability or criminal responsibility remains subject to the applicable legal process and decisions of the relevant courts.
Anti-Money Laundering Act cited
The FBR also referred to the Anti-Money Laundering Act, stating that its provisions take precedence over general laws in matters covered by the legislation.
The authority said that action based on reports of suspicious transactions from banks is taken in accordance with the law.
Banks and other financial institutions are required to identify and report transactions that raise relevant concerns under Pakistan’s financial regulations. Such reports can become part of investigations conducted by the competent authorities.
The latest ruling therefore provides clarification on how information relating to suspicious financial transactions can be pursued while associated tax matters remain pending.
Special courts to determine money trail
The FBR statement said that the relevant special courts will determine issues concerning the source and transfer of money in money-laundering cases.
This places the final determination of the financial trail and related legal questions within the judicial process.
Investigators can gather evidence, examine financial transactions and pursue cases under the applicable law, while courts ultimately assess the evidence presented before them.
The distinction between investigation and adjudication is important in cases involving allegations of financial wrongdoing, as an investigation is not equivalent to a final finding of guilt.
LHC dismisses petitions against FBR
The Lahore High Court dismissed the petitions that had challenged the FBR’s position, according to the tax authority.
The FBR welcomed the decision, saying it supports its authority to proceed with money-laundering investigations without waiting for the completion of related tax proceedings.
The ruling could provide further clarity for tax and financial investigators dealing with cases where tax-related questions overlap with suspected movement or concealment of funds.
For taxpayers and businesses facing such proceedings, the decision indicates that resolving a tax dispute does not necessarily bring a separate money-laundering investigation to an end.
Implications for financial investigations
The ruling reinforces the distinction between taxation proceedings and investigations under anti-money-laundering legislation.
A tax case may examine whether the correct amount of tax has been declared or paid, while a money-laundering investigation can examine the origin, movement and handling of funds.
Under the position outlined by the FBR, both processes can therefore take place at the same time where the legal conditions for each are satisfied.
The development is also relevant to the broader efforts of Pakistani authorities to strengthen financial monitoring and address suspicious transactions through established legal mechanisms.
The FBR’s latest statement makes clear that a pending tax case, by itself, does not create a legal barrier to money-laundering proceedings. The LHC’s decision allows the two processes to continue separately, while the relevant courts retain authority to determine the outcome of money-laundering cases.
Also read: FBR Extends Anti-Smuggling Powers Until June 2027