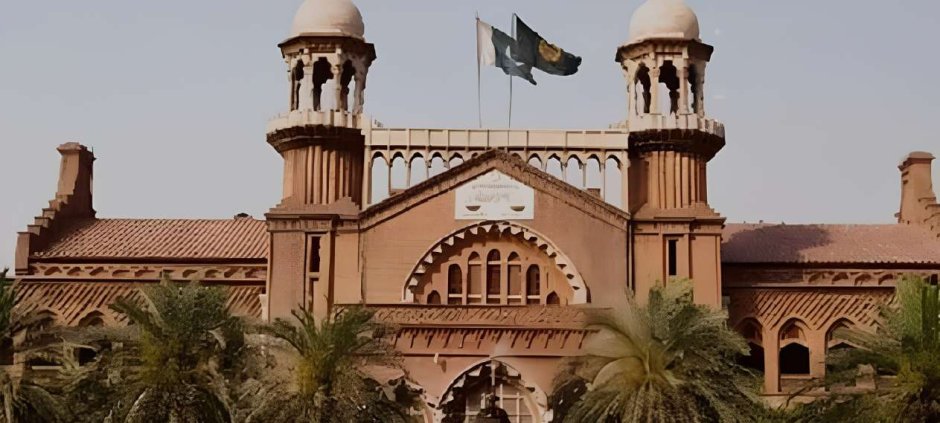
The Lahore High Court (LHC) has ruled that the Federal Investigation Agency (FIA) cannot initiate criminal prosecution against bank customers for alleged wilful loan default until a Banking Court has first established the relevant civil liability.
The decision provides an important legal safeguard for borrowers facing criminal complaints from financial institutions over unpaid loans, particularly where recovery proceedings are already pending before the courts.
In a judgment announced on October 28, 2026, a two-member division bench comprising Justice Jawad Hassan and Justice Abid Hussain Chattha allowed petitions filed by Qaiser Shabbir and others against FIA notices issued following complaints by financial institutions.
The court held that ordinary loan default and wilful default are legally different. A bank’s recovery case may establish how much money a customer owes, but it does not automatically prove that the borrower deliberately or intentionally violated financial obligations.
The ruling means that financial institutions must first establish the relevant allegations of wilful default before seeking criminal prosecution through the FIA under the Financial Institutions (Recovery of Finances) Ordinance, 2001.
The court also set aside the challenged FIA notices, declaring them unlawful and without jurisdiction because the required prior determination by a Banking Court had not taken place. <Cite refs={[“turn580107view0″,”turn580107view1”]}/>
Lahore High Court Protects Borrowers From Premature FIA Action
The petitions were filed by Qaiser Shabbir and others who challenged notices issued by the FIA under Section 160 of the Code of Criminal Procedure (CrPC).
The notices followed complaints submitted by financial institutions alleging wilful default under Section 20(7) of the Financial Institutions (Recovery of Finances) Ordinance, 2001.
The borrowers argued that financial institutions had already approached Banking Courts to recover their outstanding amounts but were also attempting to initiate criminal investigations before the underlying allegations had been conclusively established.
In some cases, recovery suits had already resulted in decrees, while other matters were pending in appeals or execution proceedings.
The petitioners maintained that a borrower could not automatically be classified as a wilful defaulter simply because a bank claimed that money remained unpaid.
They argued that the Banking Court must first examine the financial agreements, determine the relevant obligations and establish whether the alleged breach involved deliberate or intentional conduct.
The division bench accepted the petitions and ruled that the FIA notices had been issued without lawful authority because the required judicial determination had not been made.
Ordinary Loan Default Is Different From Wilful Default
One of the most important aspects of the judgment is the distinction between ordinary default and wilful default.
An ordinary default generally involves failure to fulfil a financial or contractual obligation, such as missing loan repayments.
However, wilful default involves more serious allegations, including deliberate or intentional failure to repay financing or actions that violate the obligations agreed with a financial institution.
The court described wilful default as a distinct category of default with both civil and criminal dimensions.
Under Section 2(g) of the 2001 Ordinance, the relevant allegations can involve three broad categories:
- Deliberate non-payment: Intentionally failing to repay financing after the amount becomes due.
- Diversion of funds: Deliberately using the finance, or a substantial part of it, for a purpose other than the one for which it was obtained.
- Misuse of secured assets: Removing, transferring, selling or misappropriating assets pledged as security without the financial institution’s permission.
The court observed that these allegations involve questions about contractual obligations, financial transactions, intent and the circumstances surrounding the alleged breach.
Therefore, simply establishing that money remains outstanding is not enough to prove wilful default.
The Banking Court must first examine the relevant facts and determine whether the specific conduct falls within the legal definition of wilful default. <Cite refs={[“turn955785view0″,”turn688060view0”]}/>
A Bank Recovery Decree Alone Does Not Prove Wilful Default
The judgment also addresses an important issue for borrowers whose financial institutions have already obtained recovery decrees.
The LHC clarified that a recovery suit determines the amount payable by a customer, but it does not automatically establish the separate offence of wilful default.
A bank may obtain a civil decree confirming that a borrower owes a particular amount. However, the finding that money is due does not, by itself, demonstrate that the borrower deliberately violated financial obligations.
The court explained that the Banking Court must specifically examine the allegations of wilful default rather than treating an ordinary recovery decision as sufficient proof of criminal misconduct.
This distinction is important because a customer may face genuine financial difficulties or disputes concerning contractual obligations without necessarily committing a deliberate financial offence.
The ruling does not cancel outstanding loans or prevent banks from pursuing legitimate recovery claims.
Financial institutions can continue using the civil remedies available under the law, including recovery suits, execution proceedings and the enforcement or sale of securities where legally permitted.
What the judgment restricts is the premature use of criminal proceedings under the wilful-default provisions before the relevant allegations have been judicially established.
FIA Must Follow Banking Court Determination Before Criminal Proceedings
The LHC examined Section 20(7) of the Financial Institutions (Recovery of Finances) Ordinance, 2001, alongside the Financial Institutions (Recovery of Finances) Rules, 2018.
Under the relevant provision, an authorised officer of a financial institution can submit a written complaint to the designated investigating agency after serving a 30-day notice on the borrower demanding repayment.
The FIA is designated to investigate complaints under this legal framework.
However, the court held that the 30-day payment notice cannot be used as a substitute for establishing the underlying allegations of wilful default.
According to the judgment, the Banking Court must first determine the relevant civil liability, including whether the alleged breach was deliberate or intentional.
Only after the required judicial determination can the criminal process for wilful default proceed through the mechanism provided under Section 20(7).
The bench also clarified that the FIA’s authority to investigate this particular offence comes from the Financial Institutions Ordinance and the 2018 Rules, rather than general powers under the FIA Act.
This means that the agency must operate within the limits and requirements of the special law governing banking disputes. <Cite refs={[“turn688060view0″,”turn580107view2”]}/>
Court Rejects Earlier Legal Interpretation From 2019
The judgment also disagreed with an earlier 2019 ruling by a three-member Lahore High Court bench in the case of Mian Ayaz Anwar and others versus State Bank of Pakistan.
The earlier interpretation had allowed certain categories of wilful-default allegations under Sections 2(g)(ii) and 2(g)(iii) to proceed without a prior determination of civil liability.
The latest division bench rejected that approach, explaining that all components of wilful default must be considered together because they involve underlying contractual obligations and potentially affect the amount owed to the financial institution.
The judges also rejected the practice of allowing criminal proceedings to begin and then suspending them until civil disputes are resolved.
They warned that such an approach could expose borrowers and other individuals to criminal investigations, FIRs and possible arrests over amounts that had not yet been properly determined.
The court said this could give financial institutions an excessive and potentially coercive recovery mechanism, undermining the protections available to customers under the Ordinance and the Constitution.
The judgment emphasised the importance of due process, fair trial, personal liberty and protection of property rights. <Cite refs={[“turn955785view0″,”turn688060view0”]}/>
What Punishment Does the Law Prescribe for Wilful Default?
Although the LHC has established a requirement for prior judicial determination, wilful default remains a serious criminal offence under the Financial Institutions Ordinance.
Section 20(8) provides that a person convicted of wilful default can face imprisonment of up to seven years, a fine not exceeding the amount of default, or both.
The offence is classified as cognisable, non-bailable and non-compoundable under the law.
Section 20(9) also provides additional consequences following conviction.
A person convicted of wilful default by a Banking Court becomes ineligible to receive a further loan, advance or financing from a financial institution for ten years.
The provision also restricts the convicted individual from contesting elections for Parliament, a provincial assembly or a local body for five years after serving the sentence.
These consequences demonstrate why the court considered prior judicial scrutiny necessary before criminal proceedings could begin. <Cite refs={[“turn580107view2″,”turn688060view0”]}/>
Which Borrowers Could Benefit From the Ruling?
The judgment is particularly relevant to bank customers facing complaints under the wilful-default provisions while their financial obligations remain disputed or have not been fully examined by a Banking Court.
It may also provide protection to individuals who have received FIA notices following complaints from financial institutions without a prior judicial determination of the alleged wilful default.
However, the ruling does not mean that every person who fails to repay a loan is automatically protected from all criminal proceedings.
It specifically addresses prosecution under Section 20(7) of the Financial Institutions Ordinance.
Other offences under the Ordinance or separate laws may still be dealt with through their applicable legal procedures, depending on the facts and evidence.
Likewise, banks retain their right to recover outstanding amounts through lawful civil proceedings.
Borrowers facing legal notices should therefore distinguish between an ordinary recovery dispute and an allegation involving deliberate financial misconduct.
What Happens Next After the LHC Judgment?
The petitions filed by Qaiser Shabbir and others were allowed by the division bench, and the challenged FIA notices were set aside.
The ruling provides guidance on the sequence that financial institutions and investigating authorities must follow when dealing with alleged wilful defaults under the 2001 Ordinance.
For banks, it means that criminal complaints under Section 20(7) cannot be used as an immediate alternative to establishing disputed financial liabilities through the Banking Court.
For the FIA, it reinforces the requirement to exercise its investigative authority within the limits of the special banking law.
For borrowers, the judgment strengthens procedural protections against premature criminal prosecution based solely on allegations of unpaid financing.
The decision does not erase existing debts or prevent banks from pursuing recovery. Instead, it establishes that a serious allegation of wilful default must first pass through the required judicial determination before the specific criminal process can begin.
Also read: FIA Intensifies Crackdown on Online Gambling Payments